Shareholder Activism in Indian Listed Companies: From Boardroom Whispers to Boardroom Battles
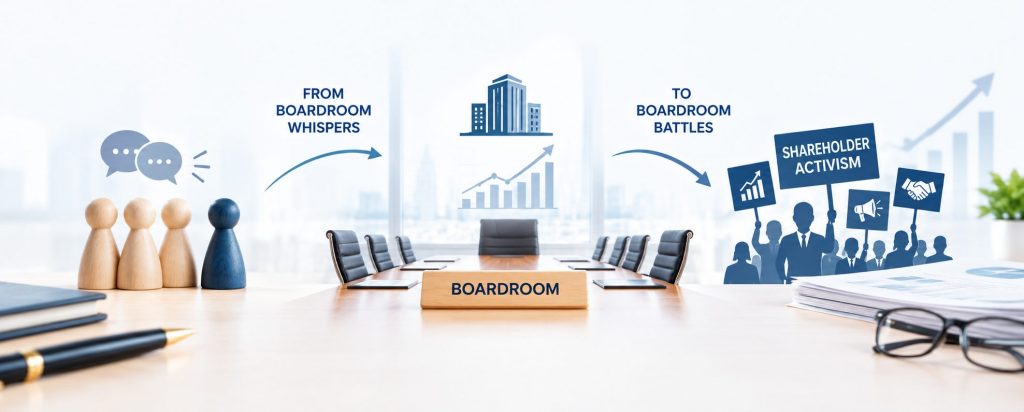
Introduction : Minority investors in India are no longer content with exiting a stock they disagree with; they are increasingly using voting power, public campaigns, and regulatory complaints to influence corporate decisions directly. What was once dismissed as a boardroom formality has evolved into a genuine accountability mechanism, driven by institutional investors, a maturing proxy advisory industry, and a stronger statutory and regulatory framework. This piece examines the legal tools available to activist shareholders in India, the role of proxy advisors and related-party scrutiny, and how to distinguish legitimate engagement from market manipulation, before outlining a response strategy for listed companies.
Legal Provisions
Requisitioned Meetings
Under Section 100(2) of the Companies Act, 2013, members holding not less than one-tenth of the paid-up voting share capital can requisition the board to convene an extraordinary general meeting (EGM). If the board fails to act within twenty-one days of a valid requisition, the requisitionists may convene the meeting themselves within three months. This is the single most potent formal tool available to activist shareholder blocs.
Removal of Directors
Section 169 permits shareholders to remove a director by ordinary resolution, following a special notice by members holding at least one percent of total voting power or shares worth at least five lakh rupees. For listed companies, Regulation 25(2A) of the SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015 adds a “majority of minority” safeguard: where a special resolution to remove an independent director fails, the removal is valid only if the votes cast by public shareholders in favour exceed those cast against preventing a promoter group from unilaterally ousting an independent director who retains public confidence.
Oppression and Mismanagement
Section 241 of the Companies Act allows shareholders to approach the National Company Law Tribunal where the affairs of a company are conducted in a manner oppressive to any member or prejudicial to the company’s interests ,the route used in the Cyrus Mistry–Tata Sons dispute, where the National Company Law Appellate Tribunal took a view favourable to the minority shareholders that was later reversed in part by the Supreme Court.
E-Voting and Disclosure
SEBI has mandated e-voting for listed companies and requires mutual funds to disclose their voting rationale, giving retail and institutional shareholders alike a low-cost way to register dissent without attending a physical meeting.
The Role of Proxy Advisory Firms
India’s proxy advisory industry led by IiAS (Institutional Investor Advisory Services), SES (Stakeholders Empowerment Services), and In Govern is regulated under the SEBI (Research Analysts) Regulations, 2014. These firms research resolutions on executive remuneration, related-party transactions, and board composition, and issue voting recommendations that institutional investors weigh heavily. Their influence has been visible in high-profile instances: proxy advisors recommended voting against Tata Motors’ executive remuneration resolutions in 2014; IiAS recommended shareholders support Cyrus Mistry’s removal from the TCS board in 2016; and InGovern’s recommendation contributed to Nestlé India shareholders rejecting a higher royalty payout to its parent in 2024. Where advisors disagree as when IiAS opposed ITC’s proposed restructuring while In Govern and SES supported it the split itself signals to the market that a resolution deserves closer scrutiny.
Requisitioned Meetings and Related-Party Scrutiny in Practice
The Zee Entertainment episode remains one of India’s clearest illustrations of formal shareholder activism: minority shareholders Invesco and OFI Global China Fund requisitioned an EGM to remove the company’s managing director and reconstitute the board, a move Zee challenged before the National Company Law Tribunal, the National Company Law Appellate Tribunal, and the Bombay High Court as procedurally invalid. The dispute demonstrated both the strength of the Section 100 requisition route and the extended litigation it can trigger when a company resists. Related-party transactions remain a recurring flashpoint precisely because they sit at the intersection of promoter interest and minority protection proxy advisors scrutinize these disclosures closely, and SEBI’s Listing Obligations and Disclosure Requirements framework requires audit committee and, beyond specified thresholds, shareholder approval, with related parties abstaining from voting, for material related-party deals.
Distinguishing Legitimate Engagement from Manipulation
Not all shareholder pressure is activism in the constructive sense. SEBI actively monitors for insider trading, market abuse, and concert-party arrangements among shareholders coordinating votes, under the SEBI (Prohibition of Insider Trading) Regulations and rules against manipulative or fraudulent dealings. Legitimate activism is typically evidence-based, channeled through statutory mechanisms such as requisitions, special notices, or National Company Law Tribunal petitions, or conducted through transparent public commentary disclosed in compliance with takeover and insider-trading norms. Reputational pressure campaigns that rely on selective disclosure, coordinated short-selling, or undisclosed concert-party voting blocs cross into territory SEBI is empowered to investigate and boards should be alert to this distinction when responding, rather than treating every activist approach as bad faith, or every hostile campaign as legitimate.
Practical Implications: A Response Strategy for Listed Companies
- Engage early and privately: global trends from the 2026 proxy season show most activism campaigns are resolved through negotiated settlement before matters go public, the same logic applies in India, where early engagement with large institutional holders can pre-empt a formal requisition.
- Audit related-party and remuneration disclosures: since these are the resolutions proxy advisors scrutinize most closely, ensuring robust explanatory statements under Section 102 and clean related-party approval trails reduces vulnerability.
- Track requisition thresholds: boards should know at all times how close any single investor or coordinated bloc is to the ten percent requisition threshold or the one percent special-notice threshold for director removal.
- Prepare a board-level response protocol: a pre-agreed process for responding to a requisition notice, including legal review, investor communication, and timelines under Section 100, avoids the reactive, litigation-heavy posture seen in disputes such as Zee’s.
- Do not conflate dissent with mismanagement: distinguishing genuine governance concerns from manipulative pressure protects both the company’s legal position and its credibility with long-term institutional holders.
Conclusion
Shareholder activism in India has matured from informal murmurs at annual general meetings into a structured, statutorily-backed mechanism for minority investor influence powered by requisitioned meetings, an increasingly assertive proxy advisory industry, and sharper regulatory scrutiny of related-party dealings. For listed companies, the lesson is less about resisting activism and more about institutionalizing a governance posture that makes activist intervention unnecessary in the first place.
Author:- Manisha Raj, in case of any queries please contact/write back to us at support@ipandlegalfilings.com or IP & Legal Filing.
Endnotes
- The Companies Act, 2013, ss. 100, 102, 169, 241.
- SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015, Regulation 25(2A).
- SEBI (Research Analysts) Regulations, 2014.
- Cyrus Investments Pvt. Ltd. & Anr. v. Tata Sons Ltd. & Ors., National Company Law Appellate Tribunal; partly reversed in Tata Consultancy Services Ltd. v. Cyrus Investments Pvt. Ltd., Supreme Court of India.
- Zee Entertainment Enterprises Ltd. — National Company Law Tribunal, National Company Law Appellate Tribunal, and Bombay High Court proceedings concerning the EGM requisition by Invesco Developing Markets Fund and OFI Global China Fund LLC (2021).
- Lexology, “Proxy Advisors: Rising Amid Shareholder Activism.”
- Lexology, “In review: recent trends in shareholder activism in India.”
- Harvard Law School Forum on Corporate Governance, “Shareholder Activism: Ten Trends for 2027” and “2026 Proxy Season Trends: The Fracturing of Shareholder Power.”
- Cyril Amarchand Blogs, “Removal of Director: Balancing Corporate Democracy with Procedural Safeguards” (2026).