Singapore Overtakes Mauritius In India’s FDI Data: Re-Testing Holding Structures
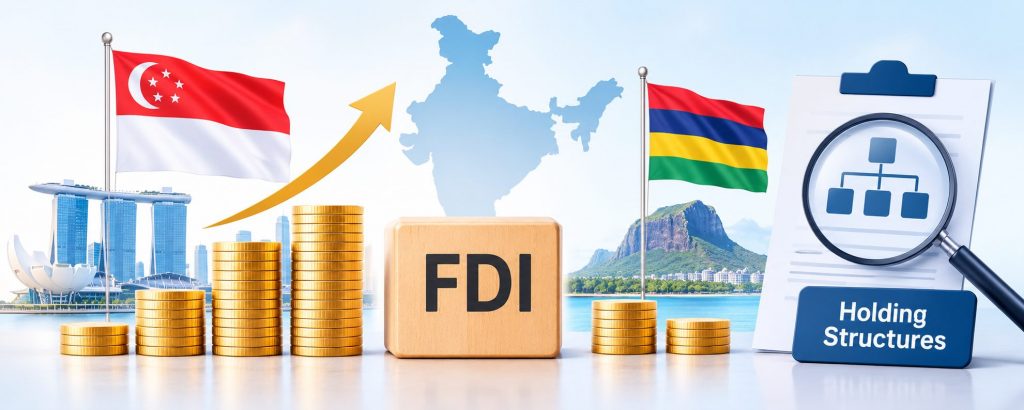
Introduction : Recent DPIIT data highlights the change in source countries of inbound FDI. Singapore has overtaken Mauritius, contributing more than 24.7% (USD 192.5B+) of the total amount of inflows, and nearly 30% of yearly inflows to equity. This shift comes from the changes in regulation of conduit companies. Countries are now requiring planning to have substance based on the minimum standards created by BEPS Action 6, PPTs and GAAR. The Supreme Court of India made a landmark ruling in 2026 in the case of Authority for Advance Rulings v. Tiger Global International II Holdings confirming that tax authorities have power to look beyond the Tax Residency Certificate and consider the true commercial purpose. This article will explore how the legal framework is changing to regulate inbound FDI. It will also discuss the key considerations around substance and tax residency, and provide a checklist of considerations for foreign institutional investors when reviewing their structure.
Legal Analysis:
In India, the legality and tax efficiency of cross-border investment structures can be understood by analysing the complex interaction between domestic statutes, bilateral double tax avoidance agreements, various circulars and foreign exchange regulations. The changes in the structure of foreign capital flow can be analysed through understanding the interplay between the domestic legislation related to taxes and international tax treaties.
Interaction of Domestic Statutory Provisions and Treaty Rights
Section 90(2) of the Income-tax Act, 1961 outlines that in the event that the Central Government has entered into an agreement with the Government of any country outside India for the purpose of relief of tax then the provisions of the Act shall apply and shall be most beneficial to the non-resident taxpayer. This provision however is subject to the following:
An investor who is a non-resident cannot claim relief under a treaty unless they have obtained a Tax Residency Certificate (TRC) that contains the required details from their country’s government. (Section 90(4)) The Indian Revenue can request additional documentation to confirm that they are a resident of the country. (Section 90(5)). The TRC has been made mandatory by the Statute but Section 90(5) ensures that it will not be used as an absolute protection against tax. (Form 10F & Form 41 (Income-tax Act, 2025)).
General anti-avoidance provisions have been included within the Statute. Chapter X-A of the Income-tax Act, 1961 (Sections 95 to 102) empowers the tax authorities to deem an arrangement an Impermissible Avoidance Arrangement (IAA). An Arrangement will be deemed an IAA if the main purpose was to gain a ‘tax benefit’ and the arrangement demonstrates any of the following factors; creates rights/obligations which generally would not be created between parties who deal at arm’s length. It results in the misuse/abuse of the provisions within the Act. There is no commercial substance within the whole or part of the arrangement. Or it has been entered into or performed in a manner not generally used for genuine business purposes. Section 90(2A) requires GAAR provisions to be applied even if they override any beneficial provisions within the DTAA. The Indian Revenue have the power to ignore offshore conduit companies by using the provisions. They can also treat capital gains as taxable income and attribute income to beneficial owners.
Treaty Preambles and the Principal Purpose Test (PPT)
Historically Double Taxation Avoidance Agreements have been interpreted in favour of enabling free movement of capital and completely avoiding double taxation. The original preamble to the India-Mauritius DTAA, pre-amendment, states that a principal aim of the treaty is to encourage trade and investment between the countries. Previously, it was accepted by the Courts that foreign investors had the right to arrange their affairs to obtain maximum tax saving.
With the introduction of the BEPS Action 6 minimum standard, the preamble to the India-Mauritius treaty has been amended to remove any reference to encouraging investment. The preamble now explicitly states that the aim of the treaty is to completely avoid double taxation, whilst having no scope for no taxation or less taxation through tax avoidance or evasion. It goes on to note that “this treaty shall not provide opportunities for no taxation or less taxation through avoidance or evasion of tax”. This change will alter the interpretation of the treaty under articles 31 & 32 of the Vienna Convention on the Law of Treaties (VCLT). When the provisions are assessed, it must be decided whether the interpretation is consistent with stopping double non-taxation and stopping treaty shopping.
Article 27B introduces a Principal Purpose Test into the India-Mauritius DTAA. This provides an objective anti-abuse rule on the treaty level which works alongside the domestic GAAR. The Principal Purpose Test can be broken down into two parts. Firstly, the objective purpose test will be applied whereby it shall be determined whether taking advantage of the treaty benefit is one of the principal purposes of the arrangement/transaction based on all the relevant facts and circumstances. Secondly, if the above criteria is satisfied then the taxpayer can rely on the object and purpose exception by proving that granting the benefit based on the circumstances would be consistent with the object and purpose of the relevant provisions of the treaty.
Residency: This will show a TRC is used to identify where the entity is resident for tax purposes. However, after Tiger Global, evidence can be provided by Tax Authorities to identify who makes key decisions. This can come from where directors are based, who approves investments and exits and where board meetings take place.
Business Purpose: A commercial purpose is one that would have been in place anyway, e.g. they need access to regional funding, they have a regional management centre or lenders/co-investors require this. One would need to evidence this prior to the transaction being made and ensure it aligns with the conduct of the entity.
The standard set out in the Principal Purpose Test differs greatly from the domestic GAAR. Under the domestic GAAR in India, the Revenue Authority must show that obtaining a tax benefit is the primary purpose to the arrangement. However, under the Principal Purpose Test, it is only required to have obtained the tax benefit as one of the principal purposes. This means there is more discretion available to the administration, and non-resident investors will be required to show there was a genuine non-tax business reason prior to undertaking the cross border transaction.
Loss of Conclusiveness of TRCs and Comparative advantage of Singapore
TRCs have been seen as conclusive evidence of tax residency and beneficial ownership in administrative guidelines for years (CBDT Circular No. 789, 2000). However, with the issuance of the Central Board of Direct Taxes (CBDT) Circular No. 7/2017, it was clarified that GAAR can be invoked even with Limitation of Benefits (LOB) or TRCs to look at the substance behind a transaction. This has also been reiterated with the issuance of the CBDT Circular No. 01/2025 providing administrative guidelines for the PPT. This provides that any intermediate structure will not qualify for treaty benefits if it lacks operational substance. There are certain grandfathering provisions provided under the circular.
With Singapore becoming the main source for foreign investments from India as opposed to Mauritius, there is a notable change in the nature of foreign investments. Early investments were driven by tax arbitrage and shell companies in Mauritius. Investments in Singapore are driven by substance. Singapore has native provisions for strong Limitation of Benefits (LOB) under Article 24 of the India-Singapore DTAA. This requires that the capital gain relief is only given if the entity meets certain criteria such as having operational expenditure of at least SGD 200,000 in the resident state in the last 24 months. Singapore also provides a good environment for setting up regional HQs, local C-suite, treasury and legal arbitration. Therefore, foreign investments routed through Singapore can demonstrate more substance, therefore meeting the PPT and GAAR.
Outside tax, investments need to follow the Foreign Exchange Management Act, 1999 and Foreign Exchange Management (Non-debt Instruments) Rules, 2019. These are governed by the Reserve Bank of India (RBI) and DPIIT. Certain provisions such as types of equity, limits per sector, route of investment (Automatic or Government) and pricing guidelines (Discounted Cash Flow Method for equity transfers) need to be met.
The law in relation to cross border investment structures in India has evolved over the years.
Case laws
Union of India v. Azadi Bachao Andolan (2003) 263 ITR 706 : The Supreme Court of India upheld the CBDT Circular No. 789 holding that a valid TRC from the Mauritian authorities shall be conclusive proof of tax residency and beneficial owner. The Court also held that as there is no express LOB clause in the bilateral DTAA, the practice of treaty shopping cannot be said to be illegal. Foreign investors shall have a right to structure their transaction in order to reduce tax liability.
Blackstone Capital Partners (Singapore) VI v. ACIT (2023) 2023/DHC/000634 : The Delhi High Court has held that the TRC has been conferred the power by virtue of Section 90(4) and hence the tax authorities cannot imply any additional requirement like beneficial ownership to claim capital gains under article 13(4) of the India-Singapore DTAA since the contracting states have deliberately not included such terms.
Authority for Advance Rulings (Income Tax) v Tiger Global International II Holdings [2026] SC 86 : The case of Tiger Global decided by the Supreme Court laid down significant principles in respect to cross-border taxation matters. This case arose from shares being transferred from a Mauritius vehicle, managed by a U.S. asset manager, to a Singapore holding company where the bulk of its value came from an Indian e-commerce company -Flipkart. Taxpayers claimed that they were exempt from Capital Gains Tax as the grandfathering provisions in the India-Mauritius DTAA Article 13(3A)/13(4) along with Rule 10U(1)(d) in the Income-tax Rules applied. The Supreme Court overturned the judgment of the Delhi High Court and laid down some significant legal principles including:
TRC Authority: A TRC is required to satisfy the initial requirements under section 90(4) but this does not prevent the Revenue Authority from exercising their powers under section 90(5).
Substance over Form: If an entity has no economic substance or is part of an avoidance scheme then grandfathering provisions under treaty protocols and/or rule 10U do not protect it from attacks using domestic GAAR.
Taxation of Indirect Transfers: If a transfer of shares indirectly occurs and those shares derive significant value from Indian Assets under Explanation 5 to section 9(1)(i) then this will still be fully taxed in India, if the intermediate offshore entity is considered to be a passive conduit.
India’s Sovereign Rights: The Court stressed that whilst India has a sovereign right to tax the value created within its borders, where no tax is actually paid in the residence state then exemptions provided by treaties should be looked at very carefully.
Practical Implications
The convergence of BEPS Action 6, bilateral protocol, CBDT guidance and the Tiger Global case law means that a complete re-examination of cross-border private equity/venture capital and corporate group structures needs to be undertaken in India. Pure shell companies in low substance jurisdictions will suffer heavily under the Principal Purpose Test. Institutional investors are focusing on investing in jurisdictions such as Singapore where there is a developed commercial infrastructure, financial activity and corporate management. Tax residency cannot be maintained by carrying out “tick box” activities. Regulators will look at a company having genuine substance such as local expenditure, employees, C-suite decision makers and business connections. Given the PPT and the onus of proof under the domestic GAAR, taxpayers should prepare contemporaneous documentation before making any investment. This includes board minutes, investment committee papers, economic justification and commercial risk analysis to set out why the chosen corporate structure was chosen for non tax reasons.
Structure review checklist for Investors
- Maintain accurate operating, commercial and fundraising documents in your investment committee minutes before any deals are done.
- Appoint independent and qualified local directors with appropriate industry experience.
- Have actual meetings of your offshore board in your resident jurisdiction.
- Have a physical office location in your holding jurisdiction with an exclusive lease.
- Employ local staff on a permanent basis for your treasury, legal and operations team.
- Spend money locally so that you meet or exceed the minimum LOB requirements, e.g SGD 200,000 in Singapore (DTAA).
- Have active treasury accounts in your local bank with authorised signatories.
- Be economically independent by making your own decisions on capital, debt repayment and dividend distributions.
- Obtain an updated Tax Residency Certificate (TRC) annually from the foreign revenue authority.
- Complete and submit all necessary disclosures to your domestic law (Form 10F/ Form 41) and local tax returns.
- Have audited annual accounts to demonstrate actual tax paid in foreign countries.
- Comply with all foreign exchange requirements, pricing guidelines and DPIIT/ RBI requirements (FEMA).
- Conduct a pre-April 2017 grandfathering check, look-through to ultimate investors, exit-tax modelling.
Conclusion
The flow of foreign direct investment originating from Mauritius to Singapore demonstrates the maturation of India’s international tax regime. The earlier simplistic approach of relying entirely on tax residence certificates and having no real anti-abuse provisions has now developed to include provisions such as BEPS Action 6, principal purpose tests under treaties, general anti-avoidance rules and judicial review.
Although the introduction of anti-abuse provisions protects the tax base, there is a need to ensure the foreign investment climate remains predictable. Therefore, it may be worth considering the introduction of bright line rules to provide safe harbour provisions. This can be achieved by expanding on the guidance provided by the Central Board of Direct Taxes. By implementing specific numerical rules such as the number of employees that need to be employed locally, a specific amount of budgeting and a specific length of time that the investment must be held, a presumption of commerciality can be created.
The Board for Advance Rulings should also have strict deadlines included in relation to the statutory provisions. In addition, the tax authorities will need to ensure that any changes made to the treaties and interpretations made by the courts are predictable.
Author:- Aishwarya Satosh Ledange, in case of any queries please contact/write back to us at support@ipandlegalfilings.com or IP & Legal Filing.
References
- Income-tax Act, 1961, Act No. 43 of 1961, 9(1)(i), 90(2), 90(2A), 95–102 (India).
- Double Taxation Avoidance Agreement between India and Singapore, signed Nov. 24, 1994, Notification No. SO 822(E), as amended by subsequent protocols including Article 24A (Limitation of Benefits).
- Double Taxation Avoidance Agreement between India and Mauritius, signed Aug. 24, 1982, Notification No. SO 782(E), as amended by the 2016 Protocol (Notification No. SO 2680(E)).
- Central Board of Direct Taxation (CBDT), Circular No. 789 dated April 13, 2000 (Clarification regarding taxation of income from capital gains under the Indo-Mauritius Double Taxation Avoidance Agreement).
- FDI Inflows Rebound: Assessing Capital Quality, PolicyCircle, https://www.policycircle.org/economy/fdi-inflows-rebound-capital-quality/
- Trilegal, Trilegal Analysis: Supreme Court’s Ruling in Tiger Global Rocks the Mauritius Treaty Boat, Trilegal Knowledge Repository, https://trilegal.com/knowledge-repository/trilegal-analysis-supreme-courts-ruling-in-tiger-global-rocks-the-mauritius-treaty-boat/
- India-Mauritius Tax Treaty: What the New PPT Means for Grandfathered Investments and Capital Gains, Business Today https://www.businesstoday.in/nri/story/india-mauritius-tax-treaty-what-the-new-ppt-means-for-grandfathered-investments-and-capital-gains-563467-2026-10-25.
- Economic Laws Practice (ELP), The India-Mauritius DTAA Protocol and the Principal Purpose Test: Treaty Entitlement, Substance and the Post-2017 Investment Landscape https://elplaw.in/wp-content/uploads/2026/07/The-India-Mauritius-DTAA-Protocol-and-the-Principal-Purpose-Test-Treaty-Entitlement-Substance-and-the-Post-2017-Investment-Landscape.pdf.
- Mauritius Treaty Benefits Cannot Be Denied Misapplying Limitation of Benefit (LOB) Clause: ITAT Delhi, TaxGuru (2026), https://taxguru.in/income-tax/mauritius-treaty-benefits-cannot-denied-misapplying-limitation-benefit-lob-clause-itat-delhi.html.
- Nishith Desai Associates, Tax Hotline: Mauritius Treaty Developments, NDA Hotline https://www.nishithdesai.com/fileadmin/user_upload/Html/Hotline/Tax-Hotline-Feb1026-M.html.