India-Mauritius Tax Treaty Amendment and Cross-Border Investment Structures
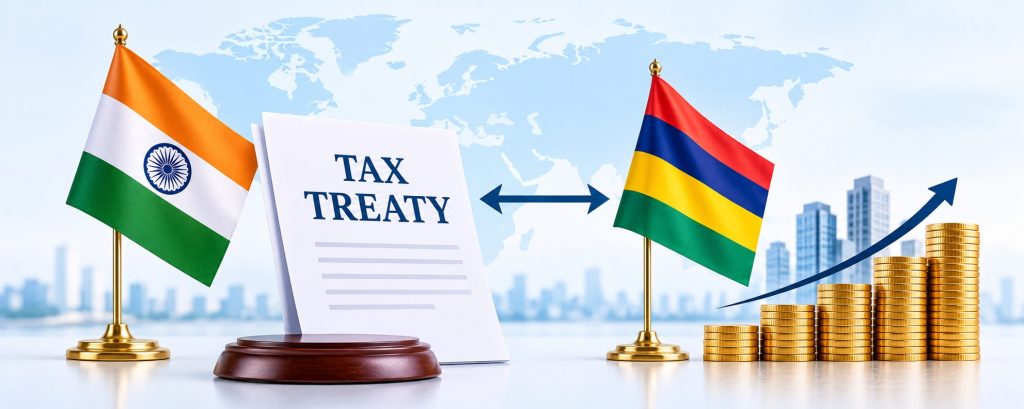
Introduction : An investment into India has traditionally taken the form of a Mauritius holding company. The treaty was welcoming, the documentation routine, and most advisers could arrange the set-up in their sleep. Many of these arrangements remain in place, some going back over a decade. That comfort can now bear scrutiny. The Protocol amending the India-Mauritius tax treaty was signed in Port Louis on 7 March 2024.
The Protocol has been reported as entering into force on 10 August 2026 and India notified this on 13 October 2026. It includes a Principal Purpose Test, and redefines the purpose of the treaty in language that is directly applicable to treaty shopping
Knowing what’s changed, how much of your current investments are protected, and how a business can check its holding structure, the associated intercompany arrangements, and the strategy for exit before a tax authority has a chance to do it for them.
What Actually Changed
The Protocol makes two changes. Firstly, it replaces the preamble and secondly, it inserts a new Article 27B entitled “Entitlement to Benefits”.
The new preamble states that the treaty shall prevent double taxation without creating opportunities for non-taxation or reduced taxation including through treaty-shopping. The older focus on promoting trade and investment has been dropped.
Article 27B is the Principal Purpose Test (or PPT). In simple language, a treaty benefit can be denied if, based on all of the information in the circumstances, it would be reasonable to conclude, having regard to all the circumstances, that the obtaining of that benefit was one of the principal purposes of the arrangement or transaction. There is a safe harbour: the benefit can be obtained if the taxpayer demonstrates that doing so would be consistent with the object and purpose of the relevant treaty provision.
Two things to note. Firstly, this is not a question of taxation being the sole reason; a commercially valid transaction can be one that is discarded on these grounds. Secondly the Protocol is reported to apply from its entry into force “irrespective of the time of the taxation or in respect of which the taxes are imposed”. That is important to remember if you thought old schemes were safe.
The PPT is not only about Capital Gains
While most comments are regarding gains on a share sale, the PPT is relevant to any treaty benefit. That might also include withholding exemption on dividends, interest and how income is derived solely from India because there is no “permanent establishment” in India. There is no fixed checklist for the PPT.
Article 27B fails to specify the number of employees, an amount to spend or a physical-presence rule. Instead, the question is whether the entity’s substance corresponds to its claimed function. The following are helpful questions: –
- What are real investment decisions and who makes them?
- Are Mauritius companies bearing the financial risk of the investment?
- Can it spend its own income independently or does the money just pass through?
- Was there a commercial reason (other than tax) for putting it in the chain?
- When was it interposed, and is that reasoning recorded?
You will still need a tax residency certificate and a Mauritian bank account but no longer these will suffice.
Grandfathering : How far does it go
The 2016 Protocol has granted India the taxing right on capital gains on shares acquired on or after 01.04.2017, and has grandfathered shares acquired prior to that date. There is a transition period at half of the Indian rate and subject to a limitation-of-benefits test. The 2026 Protocol, it is understood, does not abolish that grandfathering.
CBDT Circular No. 01/2025, 21.01.2025 backs this. It clarifies that PPT is prospective from the date of entry into force of the relevant treaty/protocol which introduced it, and clarifies that residents of Mauritius, Singapore and Cyprus will not be able to claim exemption under the PPT in respect of capital gains on pre-1 April 2017 shares of Indian companies.
But it would also be an error to view grandfathering as a free pass. In Authority for Advance Rulings (Income-tax) v. Tiger Global International II Holdings, as on 15 January 2026, the Court reinterpreted Mauritius-based investee companies that purchased Flipkart shares from 2011-15 and sold them in 2018. As per the Court’s press summary, the Court believed that the GAAR is applicable even if the original transfer takes place before 1 April 2017 and the gain on a subsequent transfer occurs after 1 April 2017; that the tax residency certificate is an eligibility condition rather than a conclusive proof; and that the authorities may probe control, management and commercial substance. Based on these facts, the exemption in Article 13(4) was denied, as the transfer was deemed an impermissible avoidance arrangement.
The logical conclusion is this. Grandfathering can shield you from the PPT and the capital gains change in the treaty. But it doesn’t necessarily shield you from domestic anti-avoidance rules, and it doesn’t help you with dividends, interest or newer investments. And each one will have to be looked at individually.
Reviewing Holding Structure and Intercompany Agreements
We’ll look at the arrangement first with the paper and then onto the particulars.
- Shareholding diagram-If you draw the chart from ultimate investor to Indian company with dates, it will be helpful. Note down the date of incorporation of entities, the date of purchase of investments and the shares in them bought before or after 1 April 2017. Be frank about each Mauritius company: what would an ignorant officer tell you it was for?
- Substance- Review minutes of board, directors, banking movements and approvals against what the organisation says. If approval/decisions are made somewhere else, your story and facts need to be changed accordingly.
- Intercompany agreements- loan arrangements, management or advisory services, licenses, shareholder agreements all warrant a closer look. Confirm that the terms are at arm’s length; the flow of cash flows really is in the agreement and that the charges, fees and royalties are truly at arm’s length and well documented. You may have lost a treaty claim to income on a document no one reads.
- Documents- For a sale, examine tax indemnities, warranties and price-adjustment provisions. If it is uncertain whether treaty protection still applies, buyers will be looking for it and sellers should be aware of what they have agreed to.
Exit Routes
Exit planning was more of an afterthought and is the point where the real danger from a treaty finally rears its ugly head. Tiger Global was on an exit. Not when they invested.
For pre-existing holdings, determine the immediate holdings (each shareholding) pre- or post-April 2017, direct or indirect and real commercial substance of the Mauritius company. Once you know which way is possible. You can sell the Indian shares, buy back the Mauritius company, buy back the Indian shares, have a market listing or restructure the Mauritius company to move the holding closer to the real principals.
There are downsides to everything. For example, a sale of the Mauritius company might produce indirect-transfer issues. An intra-group restructuring close to an exit might be the very kind of deal that activates the PPT and the GAAR. Timing, documentation and clearly-stated commercial purpose are just as important as your route to exit.
Planning Future Investment
For new investments, the PPT should be built into the transaction, not tacked on at exit. From the beginning, check whether there is a commercial rationale for setting up in Mauritius (company base, regulation, financing, co-investors) and then see if you can get the substance to match this.
Another thing is that fairer comparison can be made. The other jurisdiction or the direct investment or the fund structure may be cleaner than Mauritius, whichever is up to the investor. The amendment does not pollute Mauritius and does not mean that every Mauritian investment will now be taxed in India. It just means the claim has to be made.
Structure Review Checklist
- Build the chain-identify each entity, each owner, and each flow from the investor to the Indian company.
- Finance each investment- list funds purchased to 1 April 2017, and since.
- Test the justification- list the non-tax reason for every Mauritius company in the chain.
- Identify substance- directors, meetings and decision-making and bank activity, in relation to the alleged function.
- Check income sources- include capital gains, royalties, dividends and interests that are subject to the treaty.
- Review the intercompany agreements-ensure they are “as if from a commercial perspective, consummated, electronically executed and actually implemented.”
- Please test Gaar separately- don’t rule out anti-avoidance risk just because an investment was made before 2017 or you have a tax residency certificate.
- Plan how to quit- select a path, assess its hazard and schedule, and take note of the motivation.
- Examine the transaction files- review tax indemnities and price adjustment provisions.
- Records and diaries- make a dated record, which is checked each year.
Conclusion
The new treaty does not close the door on Mauritius, it just explains what needs to be established to pass through it. The grandfathering relieves existing shareholdings but, as the Supreme Court has stressed, it is not an end in itself. And for everything else: substance, documents and a genuine business story should do the job.
Author:- Swati Kumari, in case of any queries please contact/write back to us at support@ipandlegalfilings.com or IP & Legal Filing.
Endnotes
- Protocol amending the India–Mauritius Double Taxation Avoidance Convention, signed at Port Louis, 7 March 2024; Article 27B (Entitlement to Benefits).
- Notification No. 135/2026-Income-Tax, S.O. 5611(E), 13 October 2026 (India).
- CBDT Circular No. 01/2025, 21 January 2025 (Principal Purpose Test).
- Authority for Advance Rulings (Income-tax) & Ors. v. Tiger Global International II Holdings & connected cases, Civil Appeal No. 262 of 2026, 2026 INSC 60; 2026 LiveLaw (SC) 50 (Supreme Court of India, 15 January 2026, Pardiwala and Mahadevan JJ.).